

The card industry is at a significant turning point. In the past, a card company's competitiveness was derived from its number of members, merchants, and transaction volumes. However, in the AI era, data, algorithms, and customer experience are what determine competitiveness. Cards are no longer just plastic payment tools; they are evolving into data platforms that connect consumption, finance, distribution, marketing, asset management, and lifestyle services.
KB Kookmin Card CEO Kim Jae-kwan is at the forefront of this transformation. Rather than a traditional card company CEO, he is a manager who combines finance, strategy, digital innovation, and AI to redesign the future of card companies. Kim's entrepreneurial vision can be summarized as 'building an AI-based lifestyle finance platform.'
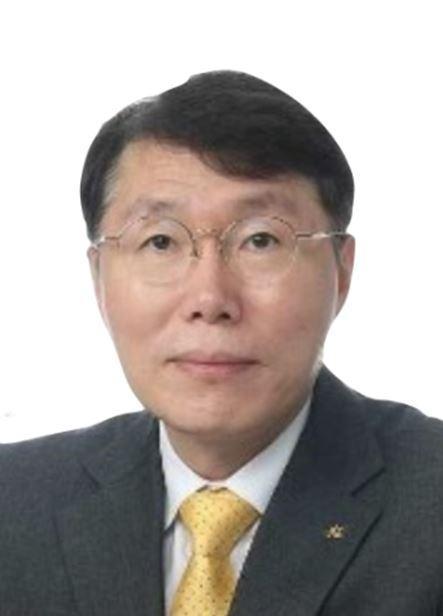
Kim Jae-kwan is a true KB man. He joined Kookmin Bank in 1992 and has worked across corporate finance, strategy, and finance, serving as CFO of KB Kookmin Bank and KB Financial Group. He is recognized for his deep understanding of capital management, profitability, and risk management, which are crucial in financial company management.
His appointment as CEO of KB Kookmin Card was not just a routine personnel change. KB Financial Group recognized that the role of card companies is changing. The traditional business model centered on transaction fees has reached its limits, with declining merchant fees, rising procurement costs, and intensified competition from big tech companies undermining the previous growth formula.
From the outset of his tenure, Kim emphasized 'execution.' In his inaugural speech, he stated that execution is the highest value. He called for a shift from being an organization that merely plans to one that delivers results.
His focus has been on AI.
Card companies hold the most consumer data among financial institutions. They know best when, where, what, and how much customers spend. In the past, this data was merely statistical information. However, with the advent of generative AI and agent AI, data is becoming a new source of revenue.
Kim aims to transform the card company from a payment entity into a data company.
KB Kookmin Card has already introduced a generative AI-based consultation service called 'Everyone's Card Life Mate.' When customers ask questions in natural language, the AI analyzes their intent and recommends suitable card products and services. This concept is closer to a financial consultation agent than a simple chatbot. To support this, KB Kookmin Card has established a RAG (Retrieval-Augmented Generation) technology and an integrated AI model management system.
This is not just a digital innovation.
It prepares for an era where AI understands customers, recommends products, and provides consultations.
The core project under Kim's leadership is KB Pay.
Traditionally, card companies interacted with customers only at the moment of payment. However, platform companies connect with customers throughout the day. Kim believes that card companies must evolve into platform companies.
KB Pay has grown into a leading platform in the card industry, boasting over 14 million subscribers. KB Kookmin Card is evolving it into a lifestyle finance platform rather than just a payment app.
In this context, AI plays a crucial role.
KB Kookmin Card is building an agent AI-based marketing system called 'AIMs 2.0,' which is among the first in the domestic card industry. This system analyzes customer data, automatically classifies customer segments, and recommends appropriate products and benefits. AI directly participates in the formulation and execution of marketing strategies.
This represents an attempt to fundamentally change the paradigm of the card industry.
In the past, humans analyzed customers.
Now, AI analyzes customers.
In the past, humans designed campaigns.
Now, AI designs campaigns.
In the past, humans recommended products.
Now, AI makes personalized suggestions.
Kim is taking it a step further.
KB Kookmin Card has recently begun developing AI agents to handle customer complaints, marketing, advertising reviews, and operational support. They are also pursuing the concept of a 'super agent' that integrates and manages these various AIs.
This is not merely automation.
AI is becoming an integral part of the organization, beyond just assisting employees.
In the future, competition among financial companies is likely to be determined not by the number of employees but by the number of AI agents.
Kim is already preparing for that future.
In the AI financial era, Kim Jae-kwan's entrepreneurial vision leans more toward sustainable innovation than aggressive expansion.
As a corporate finance expert, he emphasizes numbers and soundness. The recent improvement in KB Kookmin Card's performance stems from cost efficiency and risk management. In the first quarter of 2026, net profit reached 107.5 billion won, a 27.2% increase compared to the same period last year, achieved amid profitability pressures across the card industry.
However, Kim's true game-changer is AI.
He does not view AI merely as a cost-cutting tool.
He sees it as a means to generate new revenue.
KB Kookmin Card recently announced that, based on data from its generative AI subscription customers, the number of users increased by 413% and the amount spent rose by 516% over two years.
Many see this as just a statistic.
But Kim views it differently.
He is reading future financial demands amid changing consumer spending patterns.
In the AI era, card companies are not just payment processors.
They are the first to interpret consumer data.
That is why Kim is simultaneously advancing AI consulting, AI marketing, AI agents, and AI data businesses.
His strategy is clear.
He aims to transform card companies into financial platforms and evolve those platforms into data platforms.
There is a powerful ecosystem in KB Financial Group.
By connecting data from banks, insurance, securities, and cards, it is possible to build the largest financial AI platform in the country.
Kim's entrepreneurial spirit lies here.
He is not a CEO trying to defend the card industry's crisis.
He is a CEO experimenting with the new face of financial companies in the AI era.
Ultimately, his success will hinge on a more critical question than whether KB Kookmin Card becomes the number one card company in the industry.
Can KB Kookmin Card evolve into South Korea's top lifestyle finance platform in the AI era?
Kim Jae-kwan is the one crafting the answer to that question.
Strengths: The vast customer base and data assets of KB Financial Group are its greatest competitive advantages. CEO Kim Jae-kwan, a strategy and finance expert with experience as CFO of both the bank and holding company, excels in capital efficiency and risk management. The AI transformation strategies, including KB Pay, generative AI consulting, AIMs 2.0, and super agent development, are also industry-leading.
Weaknesses: The card industry has entered a mature phase. There are ongoing pressures from declining merchant fees, regulations on card loans, and procurement costs. The profitability of overseas operations has yet to be sufficiently validated.
Opportunities: The agent AI and hyper-personalized financial markets are rapidly growing. AI payments, AI marketing, AI consulting, and data businesses are emerging as new revenue sources. There is also significant potential for KB Pay to evolve into a financial super app.
Threats: Competition with big tech platforms like Naver, Kakao, and Toss is intensifying. There is a risk of falling behind in platform competition if AI investment slows down. Additionally, privacy protection and strengthened AI regulations pose long-term risk factors.
* This article has been translated by AI.
Copyright ⓒ Aju Press All rights reserved.