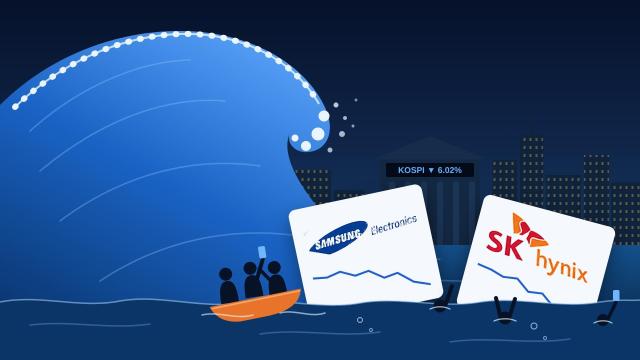
The blue shockwave from America’s midterm elections has crossed the Pacific. It delivered a rebuke to Republicans in Congress and to the White House, and for two frantic trading days it also battered the Seoul bourse, where the artificial intelligence boom had made an American vote on the cost of living painfully relevant to Korean investors.
The KOSPI closed Friday at 5,059.69, down 6 percent and lowest since February 2 as investors feared that newly elected Democrats would restrict U.S. data center construction.
Foreign investors were already heading for the exit as the results came in. They sold a net 2.5 trillion won ($1.7 billion) of KOSPI shares on Wednesday and 3.39 trillion won on Thursday, and kept selling on Friday.
Their combined net sales this year reached 247.7 trillion won through Thursday, compared with 4.7 trillion won in all of 2025.
The market, to an objective eye, is not as bad as it seems.
Samsung Electronics fell 6.35 percent to 188,700 won on Friday, about half its June peak of 374,500 won. It still trades at nearly double its price of 99,200 won a year earlier and 47 percent above the 128,500 won at which it began the year.
SK hynix lost 10.44 percent to 1,132,000 won, 62 percent below its June peak of 2,987,000 won. That is still nearly twice its price of 593,000 won a year ago and about 67 percent above the 677,000 won at the start of the year.
The KOSPI itself has lost about 45 percent from its June closing peak. It nonetheless remains about 20 percent higher this year, after soaring about 76 percent in 2025, from 2,399 to 4,214.
Simply put, the AI frenzy is cooling and the market is normalizing. There is no need for panic. Spending on AI and data centers raced ahead too fast, and chip prices overshot.
Data centers make the connection between American voters and Korean chipmakers unusually direct. Behind the seemingly weightless world of AI are warehouse-sized buildings packed with servers, processors, memory and cooling equipment.
They need land, reliable electricity and, depending on their cooling systems, substantial water supplies. Every new facility is both a market for technology suppliers and a claim on local resources.
Samsung and SK hynix sell the memory that keeps those machines working. High-bandwidth memory, or HBM, feeds data rapidly to AI processors, while servers also need conventional DRAM and storage. Fewer or later installations can therefore hit several parts of the Korean chipmakers’ business at once.
The deeper exposure is to price. Global DRAM revenue reached nearly $200 billion in the third quarter, close to five times the level a year earlier, while bit shipments rose only about 4 percent, according to Counterpoint Research.
“This is a pricing super-cycle, not yet a volume cycle,” said Jeongku Choi, a senior analyst at Counterpoint. Profits built on price rather than volume are the first to be repriced when buyers’ appetite looks less certain.
Seoul is pricing in not so much lost orders as the end of the assumption that memory prices can rise forever.
Taiwan’s chipmakers face the same underlying risk of slower AI spending, but their business is built differently. TSMC manufactures processors designed by its customers under contract, while Samsung and SK hynix sell memory whose price swings with supply and demand.
On Thursday, Taiwan’s benchmark index fell 3.20 percent, against 5.28 percent for the KOSPI and 1.79 percent for the Nikkei. On Friday, it fell 4.51 percent, against the KOSPI’s 6.02 percent.
Seoul’s pain is not unique, however. Since the end of October, Taiwan’s index has lost about 12 percent, slightly more than the KOSPI, though it remains up about 37 percent this year against the KOSPI’s 20 percent.
The AI trade is being repriced across Asia. What makes Seoul’s daily swings sharper is concentration. Samsung Electronics and SK hynix together account for roughly half of the KOSPI’s market value, so a memory scare quickly becomes a market-wide one.
SK Group Chairman Chey Tae-won acknowledged the excess before about 450 students at Seoul National University on Thursday. He said the outcome of the U.S. midterm elections had unsettled semiconductor investors and exposed the fragility of an AI-driven rally, attributing the market’s violent swings partly to excess liquidity concentrated in AI and chip stocks.
“Too much money has already been pumped into the market,” he said, warning that stocks that had risen too rapidly could also fall sharply. “These roller-coaster market conditions are bound to continue.”
Yet he remained convinced that the AI race leaves companies little choice but to keep spending. Referring to the group’s long-term investment plan of 2,100 trillion won, Chey said the scale of global competition had fundamentally changed. “The whole world is in this game,” he said. “We cannot catch up unless we make bets on this scale.”
That is the dilemma. Each company has a reason to invest aggressively because falling behind could be fatal. But when every company makes that calculation at once, the result can be more capacity than customers will profitably use.
Competition can push investment beyond what eventual returns justify, even when each individual decision appears defensible.
American voters have brought another calculation into the discussion. Households facing higher electricity bills have little reason to celebrate a data center merely because it lifts technology shares.
Communities are entitled to ask who will pay for grid upgrades, how water supplies will be protected and whether the promised benefits justify the demands on their infrastructure.
Those questions now carry political weight. Goldman Sachs estimates cited by Bloomberg put about 45 percent of planned U.S. data center capacity in states where newly elected Democrats campaigned for restrictions. Texas alone accounts for roughly a quarter of the planned capacity.
The timing is less immediate than the market’s reaction suggests. Economists cited in the same report noted that much of the capacity due to open next year is already under construction, so delays to new projects would weigh more on expansion in 2028.
A campaign promise, a permitting decision and a canceled chip order are separate events. Investors need to examine the steps between them.
There are reasons to take the risk seriously. Developers carrying heavy debt may struggle if projects are delayed, and chip suppliers could face revised delivery schedules.
But slower investment could also prevent a more damaging accumulation of excess capacity. Making developers secure power, account for local costs and demonstrate demand before building would impose useful discipline. Some projects may deserve to proceed later; others may never have deserved financing.
Seoul’s emergency response should serve a similarly limited purpose. From Monday, brokerages will be exempt from margin-loan collateral ratio rules for three months, a step that can contain a cascade of forced sales of retail investors’ leveraged holdings.
It cannot repair an investment case or erase losses that borrowing magnifies. The aim should be orderly trading while investors reassess value.
This is not a burst but a rationalization. The election has forced the AI industry to answer a question that enthusiasm too easily displaced: who benefits from this investment, and who pays for it?
The common sense of common people may help bring spending and expectations back within reach of reality. Korean investors have reason to fear a disorderly retreat. They also have reason to welcome the cooling of the fever.
*The views expressed are the author’s own.
**The author is the managing editor of AJP.
Copyright ⓒ Aju Press All rights reserved.