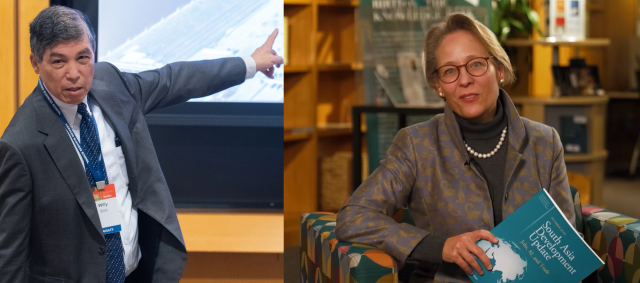
Editor’s note: In the final installment of AJP’s four-part series on the durability of the AI boom, Harvard Business School professor Willy Shih and World Bank Chief Economist for Asia Franziska Ohnsorge examine the risks facing Asia’s technology suppliers and the challenge of turning an investment windfall into lasting economic gains.
SEOUL, November 13 (AJP) - Asia’s AI boom has made its chipmakers richer. It may also be helping their next competitors get stronger — while leaving much of the region’s economy waiting for the promised productivity gains.
Those are two of the more unsettling conclusions from AJP’s video interviews with Harvard Business School professor Willy Shih and World Bank Chief Economist for Asia Franziska Ohnsorge, as questions mount over the returns on AI infrastructure spending.
For Shih, the danger for Korean memory makers is already taking shape inside the shortage that has made them so profitable. Customers unable or unwilling to pay premium prices are looking elsewhere, giving China’s ChangXin Memory Technologies (CXMT) an opening to win business and improve its manufacturing.
For Ohnsorge, Asia’s success in supplying the AI buildout leaves a larger question unanswered: how widely businesses across the region are using the technology themselves.
“That whole AI supply chain is really just producing AI. It is not using AI,” she said.
Their arguments extend the debate beyond whether an investment bubble will burst.
Even if spending continues, today’s suppliers may lose pricing power, while the broader productivity gains remain concentrated among firms already equipped to capture them.
Shih expects investment to continue at a more measured pace as providers face pressure to demonstrate returns. Ohnsorge warns that a sharp reversal would expose East Asia through two channels at once: weaker demand for its exports and turbulence spreading from U.S. financial markets.
Excerpts from the interviews follow.
The outlook — slower spending and a double shock
Q: Major American technology companies are committing enormous sums to AI infrastructure. Is this the beginning of a durable industrial transformation, or could the industry be approaching a capital investment bubble?
Willy Shih: Will the big AI suppliers, such as OpenAI and Anthropic, earn sufficient returns to justify their level of investment?
My view is that this will become more tempered over time as pressure to demonstrate a return on investment increases.
I think investment will continue, perhaps at a less frenetic pace, which could be better for the long run.
But we might experience some indigestion in the meantime. People have not fully thought through the implications of Nvidia chips being replaced by later generations, meaning the installed base becomes less valuable over time.
Will AI deliver benefits? Yes. Will those benefits be proportional to the investments being made? That is the big question.
Q: If AI-related capital expenditure slows sharply or reverses, how would the shock spread through Asian economies? Which countries would be most vulnerable?
Franziska Ohnsorge: There would be two effects.
First, if investment slows, demand for the goods that investment purchases will fall.
Those are precisely the goods supplied through the East Asian supply chain. That would be a major hit to Southeast Asian exports.
Second, U.S. financial markets would be affected, with equity markets exposed because AI-related companies now account for a large part of the S&P 500.
On the real-economy side, slower investment would mean weaker demand for exports from the region. On the financial side, you would see tightening financial conditions and an equity market correction.
East Asia differs from other regions because it is so deeply embedded in that supply chain. It would be hit through both channels.
We conducted an event study looking at what happens when the S&P 500 corrects. We examined episodes involving large corrections and asked what happens to equity markets in emerging markets and developing economies. They decline in a statistically significant way.
It is very difficult for emerging markets, including those in East Asia, to escape an equity market correction when the S&P 500 corrects.
East Asia would therefore be hit harder than other regions because it is exposed through both channels.
Korea’s memory boom — the shortage opens China’s door
Q: South Korea’s memory manufacturers are enjoying extraordinary demand and profits. What happens when additional production capacity comes online?
Shih: Right now, SK hynix, Samsung and Micron are capturing enormous value.
One reason is that capacity is very expensive, and additions to capacity are lagging demand, as they historically have in the memory business.
All the memory makers were relatively conservative about adding manufacturing capacity two years ago, but it takes a year or two to add capacity. Because memory is now in such short supply, all of them are capturing a lot of value.
The real question will arise when new capacity comes onstream and supply meets, and then exceeds, demand. At that point, the picture will be very different.
When supply exceeds demand, pricing collapses.
That has historically been the case in the memory business because additions to supply take time. When there is too much capacity, prices collapse, and everybody keeps selling because they want to keep their plants running and absorb their manufacturing overhead.
It is cheaper to keep the plants running, but financial performance then becomes terrible. That will be the real test.
Q: Korea supplies critical high-bandwidth memory, while Taiwan dominates advanced contract chip manufacturing. Which part of the supply chain has the more durable pricing power?
Shih: One company that really has pricing power—and you can see it in its quarterly earnings reports—is TSMC.
It is manufacturing chips for Nvidia and for Nvidia’s competitors, including Amazon’s Trainium.
Here, you have a situation in which capacity is constrained and there is really only one provider [of comparable advanced manufacturing capacity]. So TSMC has a lot of pricing power and captures a lot of value.
It is hard to say who is capturing the majority of the value because these companies do not disclose their margins.
The memory business is a little different from the chip foundry business.
The products are not exactly substitutable commodities because each supplier has to be qualified. Nvidia and other customers buying these memory chips want that kind of competition.
That is why the picture could be very different when memory supply catches up with demand.
Q: Does the shortage of memory chips create an opportunity for China’s ChangXin Memory Technologies, or CXMT, even though its advanced memory production yields reportedly remain far below those of Korean competitors?
Shih: For South Korean memory firms, as well as Micron, this is a very dangerous time because they are unable to meet demand for memory chips of all kinds.
They have allocated much of their production capacity to high-bandwidth memory because it offers better margins.
Meanwhile, prices for conventional DRAM and NAND flash have risen sharply, which is unusual in the history of the memory industry.
The bigger problem is that shortages have caused companies to start looking for other sources.
It is in their interest to keep memory a commodity. They do not like paying premium prices for memory because much of their profit comes from selling higher-memory configurations of their phones, tablets and computers.
The way I see the current situation, this is a golden opportunity for CXMT to exploit market shortages.
Under these circumstances, even though its yields are relatively low, it can still make a lot of money.
The key to improving yields is to work with the customers who need to qualify its products.
As you gain more experience and manufacture more, you have opportunities to refine and tune your processes. So CXMT will get better.
The most dangerous thing for Korean manufacturers right now is that this capacity shortage is opening the door to CXMT.
That is a near-term problem for which there is no easy fix.
The real test will come when new supply enters the market and prices fall. That will inevitably happen; the only question is when.
Taiwan and Japan — strengths that are hard to replace
Q: If a disruption in the Taiwan Strait temporarily disabled advanced chipmaking or packaging capacity in Taiwan, could production elsewhere compensate for the loss?
Shih: If there were disruptions to the supply of chips and materials from Taiwan, that would be a major problem for everybody globally because we have a global supply chain feeding all this computing hardware.
It would take time to make the necessary adjustments.
I think the interdependence and connectivity are somewhat underestimated.
People forget how much dependence on Taiwan remains, even though there has been substantial investment in the United States.
U.S. capacity would not even meet all of Nvidia’s needs, let alone those of Apple, Qualcomm, Broadcom, AMD or any of the others.
If that kind of disruption occurred, I think it would be much worse than people realize.
Q: Japan occupies critical positions in semiconductor equipment and specialty materials. Could its technological advantages prove more durable than those of chip manufacturers?
Shih: To the extent that the industry goes through upcycles and downcycles—whether they are booms and busts or something less severe—it is difficult to separate the rest of the supply network from those cycles.
Suppliers go through ups and downs as well. Companies such as Tokyo Electron, Advantest and some of the materials companies will experience those fluctuations.
Some of the things that are really hard to replace are materials: the fine ceramics used inside many tools, for example, along with certain exotic metals and other materials.
Across the supply chain, you have Japanese toolmakers such as Tokyo Electron and Advantest, as well as other companies that make specialized tools and are dominant suppliers in their fields.
They have been working on these things for decades, so they have a lot of experience and are not easy to replace.
The wider economy — producing AI is not using it
Q: Export earnings and higher semiconductor profits do not automatically translate into greater productivity or higher wages. What would convince you that AI is producing sustainable benefits across Asia’s wider economies?
Ohnsorge: The most important factor is likely to be how quickly they adopt AI themselves.
That whole AI supply chain is really just producing AI. It is not using AI.
Using AI productively is where the difficulty lies for emerging markets, including those in Asia.
Thailand, for example, has a strong position in the AI supply chain.
But we asked firms—not just AI firms, but firms generally—how many actually use AI.
The answer was 12 percent. How many pay for it? Four percent.
They are very good at production and deeply embedded in the production chain, but use is the missing part, at least in Thailand, where we have clear data.
That is probably a pattern affecting other countries as well.
Q: What would it take for productivity gains to reach smaller companies and ordinary workers rather than remain concentrated among large technology businesses?
Ohnsorge: That really is the main question: how do you achieve broad-based gains from AI?
One of our exercises asked firms to estimate the productivity gains they expected from AI over the next three years.
The vast majority of firms in those surveys in East Asia and South Asia expected no productivity gains, while others expected very large gains.
Our next exercise examined which firms expected larger productivity gains. It came down to precisely the traditional conditions that enable development.
The firms expecting the largest productivity gains were larger firms, but they were firms with more skilled workforces and greater existing digital capabilities as well.
Before generative AI, there was predictive AI.
We now have a dataset that allows us to track 10 years of predictive AI adoption across many firms, mostly in OECD countries but in some emerging markets as well.
We see very clearly that adoption spread rapidly among multinational corporations over roughly five years before plateauing.
Among other firms—those that are not multinationals—there was a slight uptick, but not much. By the end of those five years, or even 10 years later, fewer than 20 percent had adopted predictive AI.
To achieve broad-based productivity gains from AI across firms, one of the best things governments can do is pursue basic development policies that get the conditions right: a skilled workforce, digital connectivity and competitive pressure to adopt productivity-enhancing tools.
Basic development policy can be one of the best interventions for ensuring that productivity gains spread.
Q: Could AI make the traditional path to prosperity more difficult for emerging Asian economies by weakening demand for entry-level jobs?
Ohnsorge: In many countries, research has now shown that hiring has slowed steeply, by double-digit rates, since the introduction of AI, but very narrowly in occupations exposed to AI in a substitutable way.
These are concentrated hiring slowdowns, not necessarily job losses. They are slowdowns in hiring identified through job-posting data.
The interesting thing is that we did not find it in the Philippines, the country in our sample here. It is remarkable that we did not see the same statistically significant slowdown in the Philippine data.
But even where we do not see these hiring slowdowns, AI is already reshaping labor markets.
Returning to your question, the narrowly concentrated losses in occupations where AI can substitute for workers tend to affect entry-level workers.
But that does not mean there are no other entry-level jobs. New entry-level jobs may be those in which AI augments workers’ capabilities.
What it means is that these particular entry-level pathways have become more difficult, while others are opening up that we have not yet fully identified.
The experience of previous general-purpose technological revolutions matters: the Industrial Revolution, the internet revolution and the computer and information and communications technology revolution.
The biggest productivity gains came not simply from replacing a worker, but from changing entire production processes.
In that sense, AI can have a major effect on development once it diffuses throughout the production process.
I do not think AI closes development pathways. It opens an entirely new set of pathways that we cannot even imagine today.
That is the most likely outcome, based on previous episodes involving general-purpose technologies.
Government policy — measurable goals and affordable AI
Q: What should governments do to ensure that AI investment generates lasting economic benefits, and when should they abandon industrial policies that fail to deliver?
Ohnsorge: Governments adopt industrial policies for many reasons, some of which go beyond economics. There may be political or security reasons, and that is fine.
What is almost more important is establishing mechanisms to check whether the policy is delivering results.
Governments should define their objectives in advance: “This is what we want to achieve with the policy, and these are the milestones we will monitor to determine whether we are achieving it. If we are not, we will unwind the policy.”
That is the critical part of implementing industrial policy, which can be undertaken for any number of reasons.
Small AI is really important because it is a readily accessible opportunity for many countries and firms that cannot afford large AI models.
Small AI is the solution. It does not have to cost as much, and cost is one of the biggest obstacles to AI adoption.
Lee Jung-woo
I studied philosophy in college, and sociology and journalism in graduate school. I cover North Korea, South Korean politics, foreign affairs and films. I enjoy Nordic cinema, Indian cuisine and Japanese detective novels. I have a cat and like bright, acidic coffee.
Copyright ⓒ Aju Press All rights reserved.